WOONSOCKET, Rhode Island - CVS Health said Wednesday that it plans to separate its national pharmacy chain from Aetna, Caremark and its health-care services businesses, reversing two decades of expansion that created one of America's largest vertically integrated health companies.
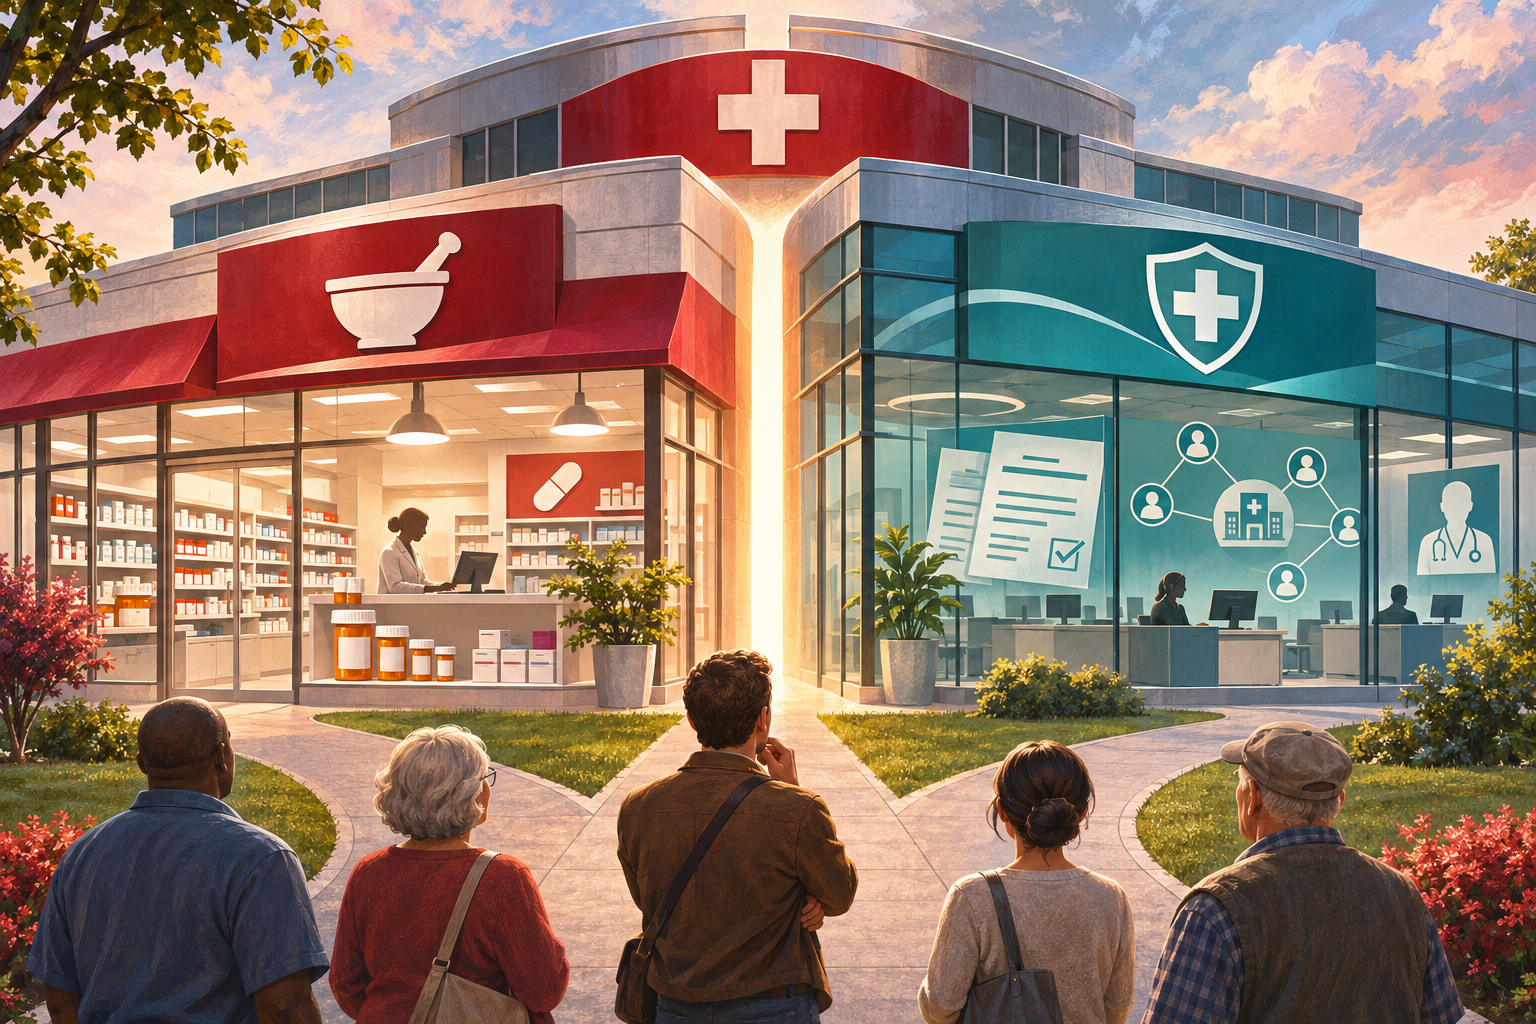
The planned transaction would create two independent publicly traded companies. One, retaining the CVS Health name for now, would include insurer Aetna, pharmacy benefit managers CVS Caremark and CVS Specialty, primary-care provider Oak Street Health and home-health company Signify Health.
The second company, to be called CVS Pharmacy, would contain nearly 9,000 retail pharmacies, mail-order pharmacy operations, MinuteClinic, virtual care and the Health100 technology business. CVS said its nearly 30,000 pharmacists would remain with the pharmacy company.
The separation is expected in the first half of 2028, subject to final approval by the CVS board, an effective registration statement with the Securities and Exchange Commission and confirmation that the transaction will receive tax-free treatment. Existing CVS shareholders are expected to own shares in both businesses.
David Joyner, CVS Health's chairman and chief executive, would lead the insurance and health-services company. Prem Shah, currently a group president, would become chief executive of CVS Pharmacy. CVS said patients, members and customers should continue receiving medicine, care, benefits and other services without interruption during the process.
The announcement unwinds a strategy built through major acquisitions. CVS bought Caremark in 2007, acquired Aetna for $78 billion in 2018 and later added Oak Street Health and Signify Health. The theory was that a company controlling insurance, prescription-benefit decisions, pharmacies and care delivery could coordinate treatment and reduce costs.
CVS described the separation as a way to give each company a clearer strategy, independent capital structure and greater ability to respond to technology and regulation. It expects both businesses to hold investment-grade credit ratings, produce strong free cash flow and pay dividends.
The company enters the breakup after a difficult period for its insurance business. Aetna was hit by higher-than-expected medical spending, prompting CVS to cut costs, close stores, change executives and exit some plans. Management said those turnaround efforts had strengthened the company enough to pursue the split.
The move also arrives amid growing scrutiny of pharmacy benefit managers, or PBMs, which negotiate drug prices and determine how prescriptions are covered. Lawmakers from both parties and several states have questioned whether common ownership of a PBM, insurer and pharmacy lets a company steer patients, restrict competition or obscure the flow of prescription-drug rebates.
The end of a powerful promise
CVS insists regulatory pressure did not drive the decision. Even so, the separation is a significant verdict on the promise of health-care consolidation. For years, large companies argued that putting more of a patient's journey under one roof would eliminate duplication and make care easier to navigate. Patients often experienced something different: complex networks, opaque pricing and fewer independent choices.
Vertical integration can create legitimate efficiencies. An insurer, PBM and care provider sharing information may identify missed prescriptions, coordinate chronic-disease treatment and negotiate lower prices at scale. But the same structure also creates conflicting incentives. The company deciding which medicines are covered can own the service that manages the benefit and profit when prescriptions are filled at its stores.
Separating the retail pharmacies does not remove all of those conflicts. Aetna and Caremark will remain together with several care-delivery businesses, and both future companies may continue commercial relationships. The details of those contracts will determine whether the split changes patients' options or merely redraws the corporate chart.
The long timeline matters as well. A transaction targeted for 2028 gives CVS room to seek approvals, allocate debt, divide technology and negotiate partnerships. It also leaves two years in which market conditions, regulation or board judgment could change the final structure. The announcement is a plan, not a completed breakup.
For consumers, the proper test is practical: whether medicines become more affordable, appeals become easier, local pharmacies remain open and patients gain meaningful choice. A more focused company is not automatically a fairer one.
For Washington, the lesson is broader. Competition policy cannot depend on corporations deciding after years of consolidation that they have become too complex. Regulators and lawmakers need transparent PBM pricing, enforceable conflict rules and evidence that mergers improve outcomes rather than merely increasing bargaining power.
CVS spent billions building an empire around the idea that bigger could simplify American health care. Its decision to divide that empire shows how difficult that promise was to deliver. The split may improve accountability, but only competition, transparency and measurable benefits for patients will prove it.
Comments
Loading comments…